
Stears and Ventures Platform have just published the most rigorous picture of African VC exits the ecosystem has ever had. The 2025 Africa Venture Capital Exit & Liquidity Report is foundational work. The SVL Index is a real contribution. Anyone trying to think clearly about African VC needs to start with it.
This is my attempt to sit with one specific finding in the report and ask what it might mean structurally, with the benefit of looking at how M&A actually works in other emerging markets at similar points in their development.
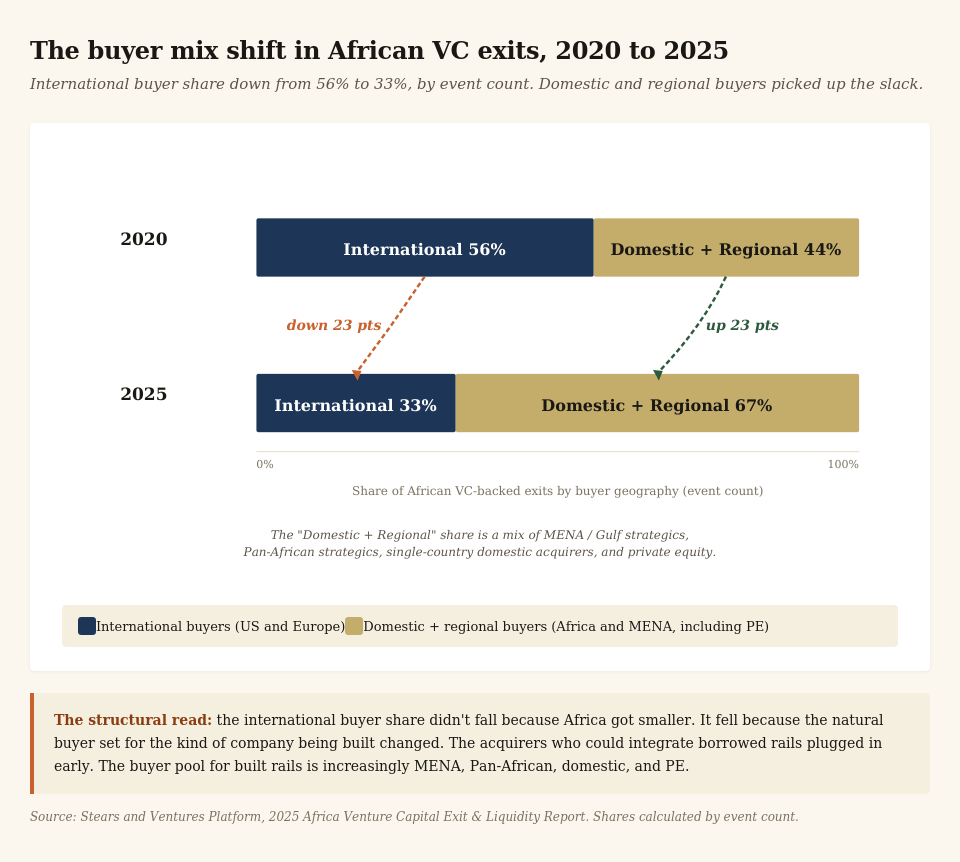
The finding is this: between 2020 and 2025, the share of African VC-backed exits going to international buyers fell from 56% to 33% by event count. Domestic and regional buyers picked up the slack. The shift holds directionally whether read by count or by disclosed value, though disclosure gaps make the latter harder to read cleanly.
The conventional reading is that international buyers ‘cooled’ on Africa. Being curious, I wondered if there’s a deeper layer to think through, as I didn’t quite feel that read was the full picture. A couple of weeks into the weeds, and with more reflection after Friday’s conversation, I think something more structural is happening. It shows up across emerging markets globally, Africa is just now showing it more sharply. My search aim here was to try and think deeply through who can actually ‘absorb’ what.
The argument of this piece, in one line: borrowed rails travel, but only to acquirers who already operate the rail. Built rails almost never travel, unless the target market is big enough to justify the acquirer creating a permanent separate operation. Africa hasn’t yet been big enough for the latter, and may not be for a while.
What follows is one way to read what we’re seeing. There are others. AI in particular is a wild card I’ll try and reflect towards end. But the patterns are visible enough to justify a discussion.
Borrowed rails and built rails.
A quick anchor for readers who haven’t been through Walk Together. With Open Eyes.
Some African startups sit on top of infrastructure that someone else owns. Payment APIs on bank rails. FX layers on per-jurisdiction licensing. Open banking aggregators on bank APIs. AI research products that plug into global pharma data and compute. The value is access to corridors, not ownership of them. Call this borrowed rails.
Other African startups are the infrastructure. A neobank with its own banking license. A payment processor with its own switch. A logistics network with its own fleet, warehouses, and last-mile capability. A solar distributor with agents in physical territory. A B2B retail platform with its own merchant network. Call this built rails.
This second category includes companies that tried to build rails and ran out of capital before reaching the scale needed to compete with entrenched incumbents. The Twiga, Wasoko, Alerzo wave of B2B commerce sits here. It became clearer that even with strong founders and backers, building rails against family-group infrastructure built over decades, takes more capital than African VC has historically had to give. They count as built-rails attempts whether or not they succeeded.
The distinction matters less when companies are raising primary capital. It matters enormously when they’re trying to exit.
When a global acquirer evaluates an African target, the question they’re really asking isn’t “is this a good business?” The question is “can we absorb this into what we already operate?” Borrowed-rails targets are easier to answer yes to, provided the acquirer already runs the underlying rail. Built-rails targets are harder, because absorbing them means either running a separate operation in Africa indefinitely, or trying to integrate something that doesn’t plug into anything the acquirer has.
Looking at many exits together helped me sharpen a potential insight.
Stripe could buy Paystack because Stripe already runs the global payment-processing rail Paystack plugged into. Paystack’s value to Stripe was access to a single regulatory corridor in Nigeria, with a product built for local context that could connect Stripe’s rails.
BioNTech could buy InstaDeep because the rail was a multi-year research collaboration that already existed. They’d been working together since 2019. The 2023 acquisition was the formalisation, not the start of integration.
Medius could buy Expensya because Medius is the European AP automation platform Expensya naturally plugged into. Different acquirer, same logic.
WorldRemit could buy Sendwave because both ran on the same mobile money and card rails. The combined entity simply had more density.
Now a refinement that matters. Not all borrowed rails are equal. It is worth pointing out a noticeable difference between a single-jurisdiction borrowed-rails business and one that orchestrates across many.
Paystack was a single-jurisdiction play when Stripe acquired it. One Nigerian PSP license. Stripe’s existing global rails could absorb that cleanly.
DPO Group, by contrast, held PSP licenses across 19 African countries by 2020. That license stack itself was the rail. Acquiring DPO meant acquiring 19 separate regulatory relationships, currency setups, and merchant networks. Network International, the Dubai-listed acquirer, paid $288M because they could absorb it. Why? Because Network already operated across multiple MENA jurisdictions and had the muscle for license-stack integration. A US buyer without that experience would have struggled to value it, let alone run it.
The starkest counter-example shows what happens when this goes wrong.
dLocal announced a $150M acquisition of AZA Finance in June 2025. AZA is a borrowed-rails business: they orchestrate cross-border FX by holding licenses across many African jurisdictions and routing currency conversion through local banking partners. A multi-license borrowed-rails business. On paper, dLocal, a global payments company with growing EM exposure, looked positioned to absorb it.
In reality, dLocal didn’t operate African rails of scale. They had a Cameroon entity and pending licenses, but not the operational depth to integrate AZA’s pan-African license stack. What happened next is documented in dLocal’s SEC filings. The deal stalled when an FTX-bankruptcy-estate lawsuit hit AZA in July 2025. dLocal extended short-term credit at 7% and 15% interest with a call option on specific assets. By the time the lawsuit was withdrawn in November and the deal finally closed in February 2026, it had been restructured: $23M for AZA’s Cameroon subsidiary only, largely paid by converting the debt facility. Roughly 15% of the announced value. The FTX lawsuit was the trigger. The structural reset was the integration problem.
So borrowed rails travel, but the more licenses and jurisdictions the rails span, the more they start to behave like built rails. They only travel to acquirers who have native experience operating across fragmented licensing regimes. Without that, even borrowed-rails businesses reset in price, reset in scope, or don’t close at all.
Built rails almost never travel.
Built-rails businesses face a different challenge. The acquirer can’t just plug them in. They have to operate them. That requires either pre-existing local presence at scale, or a willingness to run a permanent separate operation around the target.
In global M&A, that willingness exists at very specific scale thresholds.
India is the most clear-cut case. Walmart paid $16B for 77% of Flipkart in 2018. The deal worked because India is a 1.4 billion person market with e-commerce TAM that justifies Walmart running Flipkart as a permanent separate subsidiary. They made no attempt to integrate it into US retail operations and still don’t. Even at that scale, the deal has been read in subsequent commentary as Walmart accepting that organic India entry wasn’t going to work. They bought the rails because they couldn’t build them. It was a strategic concession, not a strategic win.
Southeast Asia is the second case. Alibaba cumulatively paid roughly $4B across 2016-2018 to take Lazada to 83% ownership. ByteDance paid $1.5B for 75% of Tokopedia in 2023. Both are built-rails e-commerce platforms in a region of 650 million people. Both acquirers are Chinese strategics that already operated logistics, marketplace, and payments rails in their home market and had organic Asia integration capacity. The equivalent Western deals (Amazon acquiring SE Asia, Google buying SE Asia tech) never happened at comparable scale.
MENA gives us two cases that test the upper bound of when this can work with Western buyers. Uber paid $3.1B for Careem in 2019 to acquire MENA ride-hailing infrastructure. Amazon paid $580M for Souq in 2017 to acquire MENA e-commerce infrastructure. Both were Western buyers acquiring built regional rails. Careem had operations in 14 countries with regulatory licenses, driver networks, and payment relationships across the region. Souq had warehousing, last-mile logistics, and merchant relationships at MENA scale. In both cases, the acquirer paid scale-justifying money because the aggregated MENA market of around 400M people, with growing dollar GDP, was just big enough. Notably, both deals also struggled with integration. Uber-Careem took years to integrate operationally. Amazon-Souq involved significant rebranding pain. The scale was there, just barely. Sub-Saharan Africa is roughly comparable to MENA in aggregate population but materially smaller in dollar GDP and consumer spend, so the threshold those two cases just cleared, sub-Saharan plays haven’t reached yet.
Latin America has produced almost no Western built-rails acquisitions through M&A. Uber paid $1.4B for Cornershop, but only after Walmart’s attempt was blocked by Mexican antitrust, and only because Uber already had operations across Mexico, Chile, and Colombia. Even then, Uber struggled with integration. The largest LatAm M&A is mostly domestic: StoneCo buying Linx ($1.1B), Nubank’s serial roll-ups, Mercado Libre’s ecosystem plays. What LatAm has done instead is taken its larger built-rails businesses to US public markets, where Stone, PagSeguro, Nubank and dLocal collectively now represent tens of billions of dollars of LatAm-tech market cap on NYSE and NASDAQ. The exit happened, just not through acquisition. This option in Africa exists, but with a material nuance.
The pattern across all four regions: built-rails businesses travel to global buyers only when the target market justifies a permanent separate operation, and even then, integration tends to be painful. That threshold is roughly Flipkart-Lazada-Careem scale. Hundreds of millions of consumers across the aggregated regional footprint, multi-billion-dollar deal sizes, acquirers willing to run the business indefinitely as a stand-alone unit.
Africa’s market fragmentation affects scale. No single African market hits Flipkart-Lazada population or TAM. Pan-African plays operating across 3-5 markets aggregate to populations and GDPs that wouldn’t justify a major Western strategic running a permanent African subsidiary on the Careem-Souq model. The math doesn’t work, not because Africa is unattractive, but because the integration cost is largely fixed and the addressable revenue not yet large enough to amortise it. This isn’t an Africa problem so much as a global EM pattern showing up sharply here, given Africa is the smallest of the four EM regions by aggregate VC-scale revenue. The underlying logic applies everywhere.
Looking at the data through this prism: the international buyer share didn’t fall because Africa got smaller. It fell because the natural buyer set for the kind of company being built changed.
The MENA exception, in global context.
Not every cross-border buyer behaves like a US or European acquirer. MENA buyers, Gulf strategics in particular, show up as a distinct category in the African data.
Network International’s $288M acquisition of DPO in 2020. Dubizzle Group buying Hatla2ee in Egypt in early 2025. Baims (Kuwait) acquiring Orcas (Egypt) in January 2024. AYEN (Saudi) acquiring Elmawkaa in 2024.
These targets are payments processing, classifieds with local content moderation, edtech with tutor networks. Built-rails or multi-license borrowed-rails businesses in regulated sectors. The kind of business a US buyer would discount heavily.
What MENA buyers have that Western buyers don’t is operating capacity for jurisdictional fragmentation as a native condition. A Gulf operator runs across 8-18 MENA jurisdictions with different banking, FX, telecom, and consumer protection regimes. They are familiar with Africa’s fragmentation. It’s an extension of their home operating model. Network buying DPO is the clearest case. The same regulatory-multiplicity muscle that runs Network’s MENA payments business is the muscle DPO’s 19-country license stack required.
This is the same dynamic visible in SE Asia, where Chinese acquirers have organic regional integration capacity that Western acquirers don’t. China is to SE Asia what the Gulf is to Africa. The regional incumbent with multi-jurisdictional operating muscle. Latin America doesn’t have a clean equivalent (Mercado Libre is the closest, mostly through investment and strategic partnership rather than acquisition).
For African founders, this matters more than it usually gets credit for. The natural buyer for an Egyptian or North African built-rails business is probably Gulf, not Western. For sub-Saharan built rails, the natural buyer is more likely Pan-African or domestic, because Pan-African strategics with multi-market presence are still emerging, the pool is smaller than MENA’s, and the largest deals (DPO at $288M is the high water mark) require the acquirer to already have continental ambitions.
The implication: if you’re building built rails in Africa, your acquirer pool is structurally different from what your investors might be modelling, and probably not who they were modelling.
The sub-$100M domestic story.
The other half of the buyer mix shift is African-to-African M&A. It’s now real, but at a specific size band that the headline doesn’t always capture. Most disclosed African domestic acquisitions sit below $100M, and a good share sit below $25M.
A few examples from 2022-2026:
Nedbank acquiring iKhokha for ~$93.9M cash. South African bank with licenses and balance sheet buying SME payments fintech with tech and merchant relationships.
Flutterwave acquiring Mono for an estimated $25-40M (TechCrunch sources). Payments scale-up buying open-banking API layer.
FairMoney acquiring PayForce for an estimated $15-20M. Neobank buying merchant/agent banking capability.
Risevest acquiring Hisa (and earlier Chaka). Nigerian wealth-tech buying Kenyan CMA-licensed broker.
Stitch acquiring ExiPay and then Efficacy Payments in South Africa. Online payments buying in-person POS and DCSP card-clearing license.
OmniRetail acquiring Traction Apps. B2B retail platform buying merchant POS.
MFS Africa (now Onafriq) acquiring Capricorn Digital / Baxi in 2022. Pan-African fintech buying built rails. Nigeria’s largest independent SME agent network, 90,000+ agents processing $1.6B annually. Capricorn’s CEO described the deal as the second-largest Nigerian fintech transaction at the time, behind Paystack-Stripe.
The pattern is consistent. An acquirer that has either license (Nedbank), tech distribution at scale (Flutterwave, Stitch, FairMoney), or regional reach (MFS Africa) buys the missing piece. Call it license-plus-tech arbitrage, or in MFS-Africa-Baxi’s case, reach-plus-rails arbitrage. The deal works because both sides know exactly what’s being acquired, integration cost is local, and the price reflects strategic fit and EBITDA contribution rather than growth-story multiples.
This is, broadly, the same pattern visible in other EMs at the same development stage. India’s HDFC Bank-Citi consumer arm, Axis Bank-Citi India, Tata acquiring BigBasket, Reliance’s serial roll-ups. Brazil’s StoneCo-Linx, Nubank’s acquisition string. These are domestic licensed incumbents, or domestic tech-at-scale, buying smaller tech-capable startups for integration into existing distribution or to add a missing capability.
What’s different about Africa right now is the depth of the buyer pool. India has dozens of large public corporates with M&A budgets sized to a 1.4B-person consumer base. Brazil has StoneCo, Nubank, Itaú, Mercado Libre, and a handful of others operating in a 215M-person market with deep capital markets. Africa has, depending on how you count, perhaps 10-20 repeat strategic acquirers across all sectors: JSE-listed corporates with predominantly SA exposure, a handful of Nigerian banks, some Egyptian financial groups, a thin set of Kenyan listed companies. Most operate in single-country markets that are individually small. That’s an actual constraint on both the number of deals possible at any given moment and the size band any single acquirer can stretch to.
My point is not that Africa M&A is ‘weak’, but more that our acquirer pool needs to grow (in count, in muscle, and in regional reach) for the path to scale up.
The fifth (and important) buyer category: PE. Helios, DPI, Adenia, AfricInvest, Apis, Investec, Actis, and a growing set of Gulf-anchored PE shops are active acquirers of African VC-backed companies, particularly built-rails businesses with EBITDA. PE buyers price on cash flow, not growth multiples, so headline values tend to be modest. But the channel has substance that invites more weight in VC fund models at this time. For built-rails businesses that have crossed into profitability but won’t reach public-market scale in this cycle, PE is often the cleanest path. For VCs and DFIs, the implication is that the buyer pool to build relationships with is both strategic and financial.
A structural feature to design around, not a problem to solve.
The disclosure problem behind all of this.
A pause here, because everything I’ve just argued sits on a thin epistemic foundation.
Stears reports that only 12% of African VC exits have disclosed values. The AZA case shows what the disclosure gap hides. The press release said $150M. The SEC filing said $23M for a subsidiary, mostly debt conversion. If a NASDAQ-listed acquirer hadn’t been required to file, the press release would still be the public record.
The gap is about deal size as much as it is about deal structures. Earn-outs and liquidation preferences also matter, as do debt conversions and markdowns. The reasoning in this piece, and in every piece anyone writes about African VC exits, rests on a sample already self-selected for the deals worth disclosing. Within that sample, deal structure is mostly invisible.
Africa sits at the bottom of the disclosure ladder among the four EM regions, partly because its acquirer pool is dominated by private operators with no filing obligation. The patterns I’m describing are consistent with the data we can see and with how M&A works in comparable markets. They’re directionally defensible, not provable with the rigour you’d want. This is the strongest argument for transparency as the lowest-cost, highest-compounding ecosystem intervention. Better disclosure wouldn’t change the structural reality. It would let the ecosystem read its own reality more accurately, price for it, and adjust faster. Stears flagging the 12% number is itself a contribution.
Build rails at scale, and the public market question.
I want to come back to where built-rails businesses can actually exit, if global acquisition is mostly off the table and domestic acquisition tops out around $100M.
Inferring from many EMs, it looks like the natural exit for built-rails-at-scale is the public market. Indian tech IPOs scaled massively between 2021 and 2024 (Zomato, Paytm, Nykaa, Policybazaar, FirstCry, Mobikwik), all on Indian exchanges, in a market with the depth to absorb $5B+ tech listings. SE Asia saw GoTo list on IDX in 2022, Sea Limited on NYSE in 2017, Grab via SPAC on NASDAQ in 2021. LatAm took its largest built-rails businesses to US markets: Stone on NYSE in 2018 (~$8B at IPO), PagSeguro NYSE 2018, Nubank NYSE 2021 (~$45B), dLocal NASDAQ 2021.
In Africa, that channel is thin. Egypt has seen Fawry list on EGX in 2019, the first Egyptian fintech IPO, and Valu list via in-kind distribution from EFG Holding in June 2025, with Amazon picking up a 3.95% stake on first day. Bosta is reportedly preparing to list on EGX by end of 2026 at roughly $160-170M, which would be the first VC-backed Egyptian logistics IPO of any material size. South Africa has JSE-listed tech-adjacent businesses with regular trading volume. The JSE is the only African exchange with the depth to absorb $5B+ tech listings. Nigeria’s NGX tech listings are thinner.
The question is who can use it, and at what scale. The constraint that doesn’t get talked about enough is exchange size itself. The total EGX market cap is around $60B as of end-2025, after a 42% rally during the year. The largest single Egyptian listing, Commercial International Bank, sits at roughly $8B. The NGX equity market cap reached ~$69B by end-2025, after a 51% rally. The largest Nigerian-listed company, Dangote Cement, sits at ~$5.8B. The JSE has multiple companies above $20B and is the only African exchange with depth comparable to mid-sized global markets.
That has direct implications. A $1-1.5B African tech IPO can list on EGX or NGX in principle. Bosta at $160-170M is well within range. Fawry at ~$1.1B sits comfortably. A larger built-rails play, say a Wave or Moniepoint at $5B+ aspiration, runs into structural constraints. A $5B IPO would be ~8% of the entire EGX market cap and dwarf both CIB and Dangote Cement by a wide margin. Egypt and Nigeria face the same scale constraint. South Africa can absorb larger listings, but the JSE is mature and competitive, with listing infrastructure built around traditional corporate categories more than venture-backed tech.
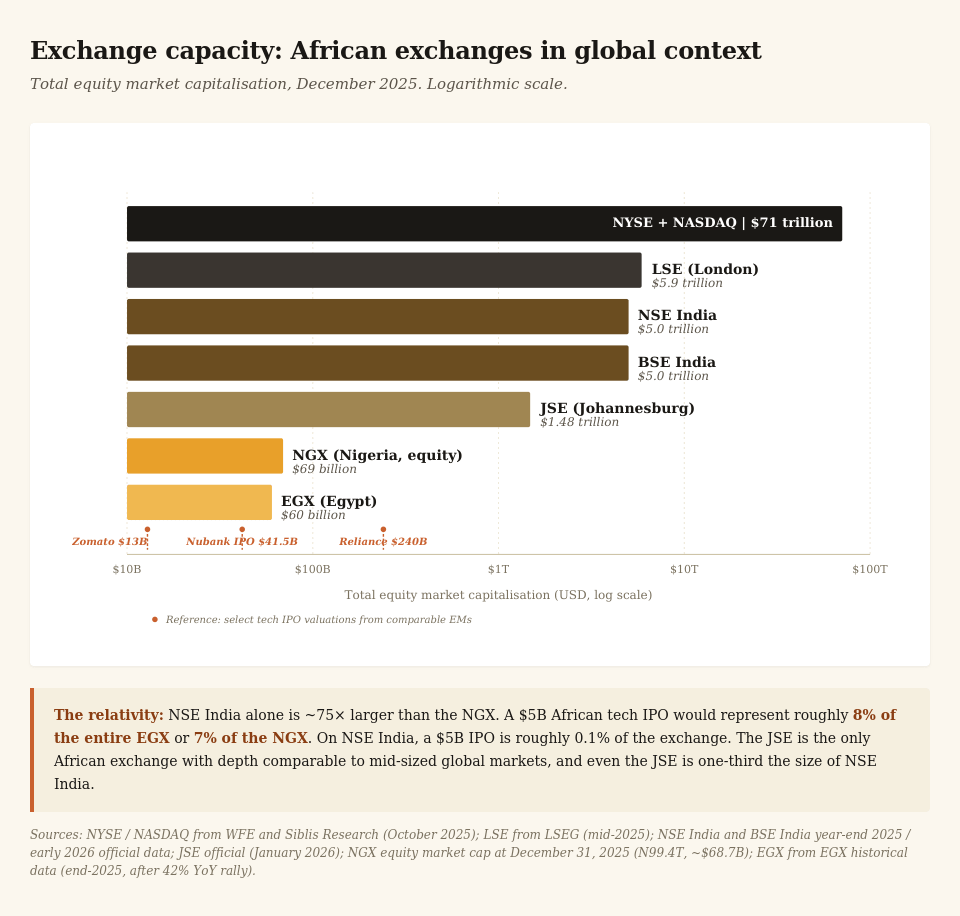
So African built-rails businesses at sufficient scale have three possible exit channels and none of them are easy. Domestic listing (works up to about $1-1.5B in Egypt/Nigeria, up to ~$20B+ on JSE). Foreign listing (London or New York, requires significant scale and accounting infrastructure, plus FX risk management on Naira, EGP and other local currencies). Or strategic acquisition by a buyer big enough, which puts us back in the Walmart-Flipkart scale problem.
Over the years I have sometimes heard people raising a question about which African founders can credibly build to public-market scale at all. While I firmly believe it is a ‘yes’, I want to unpack where it might come from.
Fawry deserves a more careful look here. By the time it listed in 2019, it had been running for 11 years, processed billions of transactions on its own switch, and built proprietary infrastructure connecting 36 banks. By any measure it’s a built-rails success.
Fawry was not a venture-startup story in the conventional sense. It was founded in 2008 by Ashraf Sabry, a senior IBM and Raya Holding executive who’d already taken Raya public, in partnership with the Egyptian banking system. Early investors included Arab African International Bank, HSBC, Alexbank, and IFC. The 2015 round was a $100M consortium of Helios, MENA LTV, EAEF, and IFC. Sabry himself ended up with roughly 2.3% of the company at IPO. A version of the same pattern is visible at Interswitch (founded with Nigerian banks as co-founders) and at Optasia (telco relationships from parent Channel VAS).
To be clear, this is at best an observation with not too much to infer from. One path to public-market scale in Africa has historically run through founders who came in with institutional relationships already in hand. That path is visible and worth understanding. It is by no means the only path.
The more interesting question is what an independent VC-backed founder building toward built-rails scale actually needs to do, given that they often don’t start with those incumbent relationships. Practical advice here is: build them on the way up, deliberately, as part of the company strategy. Wave’s expansion across Francophone West Africa has involved years of central-bank engagement under WAEMU. Moniepoint’s relationship with the CBN was built progressively. Onafriq’s continental footprint required licensing relationships in 40 markets. The point is that the ‘institutional layer’ can be built if it is not inherently present. It just has to be treated as a load-bearing part of the company-building work.
The test cases for whether VC-backed founders can ride the build-rails-to-IPO path in Africa are now live. Wave in Francophone West Africa. MNT-Halan in Egypt. Bosta as the most immediate test, with an EGX listing reportedly targeted by end-2026 at $160-170M. None is a guaranteed outcome. But the path looks more open than it has historically, partly because the regulator-engagement playbook has matured, partly because exchanges in Egypt and South Africa are warming to tech listings, and partly because the founders themselves are spending serious time on the relationship side of company-building.
Built-rails plays that grow beyond what NGX or EGX can absorb still face a mid-cap gap. Too big for domestic listing, too operationally complex for foreign listing without deeper accounting infrastructure, too small for global strategic acquisition. That’s where we are today: a ‘point in time’. It’s also where India was in 2015, before Indian exchanges deepened enough to absorb Zomato and Paytm. The gap isn’t permanent, but closing it may take longer than a venture-fund timeline.
What this might mean for founders, investors, and the ecosystem.
The data shows a pattern that’s consistent with how other EMs have evolved at similar stages. But “consistent with” isn’t “destined to be,” and Africa has features (demographics, AI, energy transition dynamics) that may produce paths none of us are modelling yet. So what follows is considerations, not prescriptions, and I want to frame them as useful rather than corrective.
For founders. The most useful question is: what’s the natural acquirer set for what I’m building, and have I made that explicit as part of my strategy, not just my pitch?
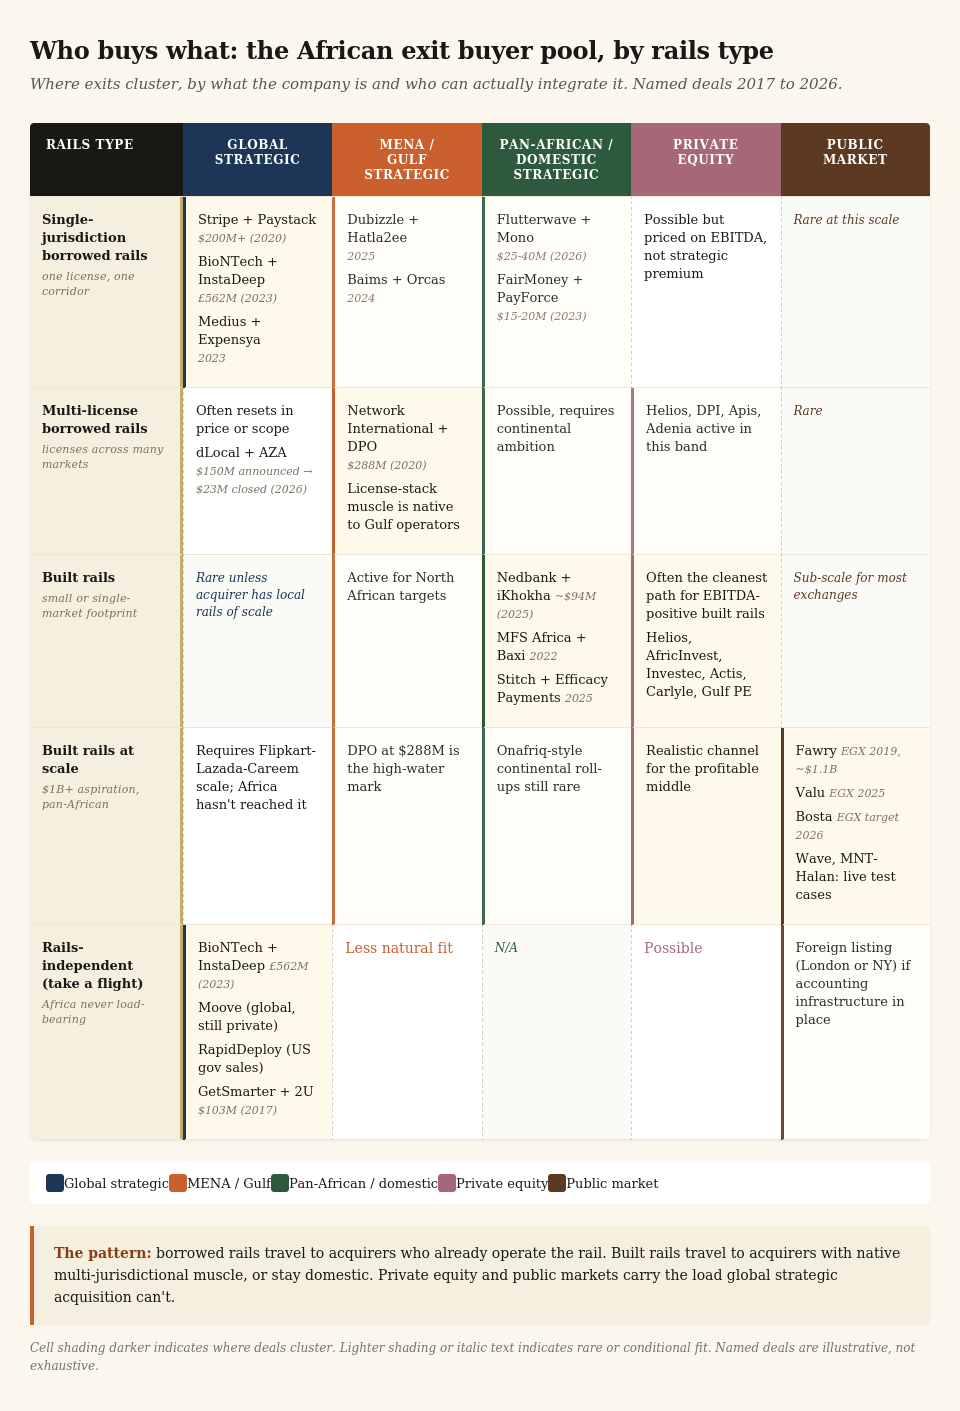
For borrowed-rails businesses, the global exit path exists, but only to acquirers who already operate the underlying rail. Make the list at Series A. Two acquirers is fine, one is fine, zero is signal. The more licenses or jurisdictions your business spans, the more your acquirer set narrows toward buyers with native multi-jurisdictional operating muscle (Network International, Onafriq, certain Gulf strategics). For built rails in a single or small multi-market footprint, the natural acquirer pool is domestic, regional, MENA, or PE. Deal sizes have clustered below $100M, with implications for what capital you raise and at what pricing. For built rails at scale, the realistic path runs through a domestic listing, a foreign listing, PE, or eventual strategic acquisition by a buyer big enough.
The deeper move is to treat the buyer relationship as something you build over time, not something you discover at the end. That doesn’t mean putting a strategic on the cap table at Series A is always the right answer. Sometimes it is (Stripe led Paystack’s Series A and acquired two years later). More often, an early strategic investor caps your acquirer optionality, lowers your eventual price, or creates governance friction at the moment you most need flexibility. The better default is to build relationships with two or three likely acquirers without giving them shares too early. Commercial partnerships. Co-launched products. Joint regulatory submissions. Shared customer pilots. These are the substrate that make an eventual pricing conversation start at a number that reflects strategic value, not just EBITDA. The Paystack-Stripe deal didn’t happen because of one Series A check. It happened because by 2020 Stripe couldn’t enter Africa without buying Paystack, and Paystack had spent two years making sure that was true.
For founders building built-rails businesses at scale, founder-secondaries require understanding earlier than most founders realise. Partial liquidity in late primary rounds (the Moniepoint Series C model) is now a real mechanism for de-risking personally while staying committed to a 10-15 year build. I hope these become more ‘normalised’ and encouraged by investors, as it can change the calculus on whether to take the longer path at times.
If what you’re building is genuinely independent of African rails (InstaDeep, Moove, GetSmarter, RapidDeploy patterns), the rails question doesn’t apply. The acquirer pool is global because the company never depended on African rails. AI may expand this category, though it's hard to generalise to most African startups. It requires deep technical specialisation or a globally-portable product from day one.
None of this is to take away from the correct and huge ambitions of some founders. The acquirer pool isn’t a fixed set you have to optimise within. Some of the outstanding companies will expand the pool by demonstrating that what they’ve built is more strategically valuable than the obvious buyers would naturally compute. These founders aren’t picking from a fixed menu of acquirers, and some are building infrastructure that may prove meaningful for global players entering Africa over time. That’s a slow build, mostly invisible from the outside, but it’s where some of the biggest African exits will come from in the next decade. My one ask is to try hold the value-creation strategy and the eventual liquidity moment in the same frame from early on. Both founders and their backers benefit when the path to a meaningful exit is part of the build, not just an afterthought.
For investors. The most useful frame is matched fund construction. Fund size, hold periods, LP composition, and carry mechanics need to match the realistic exit profile of the portfolio, not a template inherited from a different market and stage. A borrowed-rails portfolio with clear global-acquirer-with-rails matches can model standard venture exits. A built-rails portfolio needs to model longer holds, smaller domestic exits, public-market liquidity that may take 10+ years for the largest plays, and PE as a serious channel for the EBITDA-positive middle. These are different products and probably need different fund shapes. Acknowledging this in fund design and LP communication lets the asset class build credibility from delivering against well-set expectations rather than missing aggressive ones.
A second move follows. African VCs and DFIs spend most of their networking effort on the inbound side (sourcing founders) and relatively little on the outbound side (building relationships with eventual buyers). For built-rails portfolios, that ratio probably needs to shift. The buyers who matter are JSE-listed corporates, Egyptian and Nigerian banks, Pan-African scale-ups like Onafriq and Flutterwave, Gulf strategics, the PE shops named above, and the bankers at EFG Hermes and Renaissance Capital who manage local IPOs. Knowing them, being known by them, and helping portfolio companies engage them three to five years before an exit conversation may be the difference between a sub-$50M exit and a $150M one.
This applies especially to DFIs, who sit on both sides of African VC: as LPs in the funds, and as direct equity holders in many of the larger built-rails businesses themselves. That dual position is unusual and underused. They already have institutional access to most of the counterparties above, and the tools they bring (blended capital, longer holds, mandates that value in-region continuity) let them shape exit outcomes in ways commercial LPs structurally can’t. Making this part of a structured program for GPs and portfolio companies, not an ad-hoc favour when an exit is already on the table, would be a useful starting point.
For the SVL Index’s next iteration, two extensions would be especially additive. One is classifying exits by buyer category and rails type, since a $200M international acquisition of a borrowed-rails business is structurally different from a $50M domestic acquisition of a built-rails one, which is different again from a $1B public listing or a $40M PE buyout. The other is reading the secondaries story in both percentage and absolute terms. Secondaries growth in Africa is a positive and useful development. In percentage terms, African secondaries are still below mature-EM par, where they typically run 10-15% of total liquidity. In absolute size, the gap is much wider. Reported African secondaries are mostly sub-$10M transactions inside larger primary rounds (Oui Capital’s $8M partial exit from its $150K Moniepoint seed is among the more visible cases), where Indian, Brazilian, and SE Asian secondaries routinely clear $100M+. Disclosure gaps make this picture worse, not better. Secondaries growth, however welcome, is not yet a solution to the capital-return-at-scale problem African VC still needs to solve. A future SVL iteration that tracks absolute dollars distributed to LPs alongside event count and Quality sub-scores would help the ecosystem read the difference between deal activity and actual return of capital.
A related mechanism worth watching is continuation vehicles and GP-led secondaries, which India saw scale rapidly between 2020 and 2024 and which African GPs are starting to explore, buying time on portfolio companies that need more years to reach IPO or strategic-exit scale. It doesn't solve pricing tensions on its own, but other ecosystems have used it as a real tool on their path to liquidity maturity.
What AI does to this picture.
A genuine wildcard I don’t think anyone has clean answers on yet. AI changes two things that matter for this framework.
First, it may expand the take-a-flight category. InstaDeep was the first major African-built-rails-irrelevant exit. Moove built a global business from Lagos. RapidDeploy sells emergency dispatch software to US county governments from Cape Town. If AI lowers the cost of building globally-competitive software from anywhere, which it appears to, more African founders may end up in the category where rails don’t apply because the product was never about Africa in the first place.
Second, AI may reshape what borrowed and built rails even mean. If an AI-native fintech doesn’t need physical agent networks because language-model interfaces handle customer onboarding, or if AI-native logistics doesn’t need fleet ownership because predictive routing makes asset-light models viable, then the borrowed/built distinction itself becomes more fluid. Some of what is built rails today may become borrowed rails tomorrow. New infrastructure layers may emerge that don’t fit either category cleanly.
I don’t have a strong prediction. What I’d watch: whether the next wave of African AI companies follows the InstaDeep model (Africa-based, globally-sold) or the Moniepoint model (Africa-built, Africa-operated), and whether global AI strategics emerge as natural acquirers of African AI plays, which would echo the borrowed-rails-with-existing-acquirer-rail pattern from 2018-2020. The reality is we don’t know yet. AI might rewrite parts of this framework.
Closing.
Stears and Ventures Platform have given the ecosystem its clearest exit picture yet. The shift they describe, international buyer share down from 56% to 33%, is real and measurable. The reading I’ve tried to develop here is that the headline isn’t just about appetite. It’s about integration capacity, and the kind of company being built has shifted in a way that changes the natural buyer pool. Borrowed rails travel to acquirers who already operate the rail, while built rails struggle to travel as far without scale to justify a permanent separate operation. The natural buyer pool for African built-rails companies is increasingly domestic, MENA, PE, or at sufficient scale and over a long enough horizon, the public market.
As argued before, African VC isn’t broken. But the dominant exit channels look different from what a Silicon Valley model would predict, probably more like what India, SE Asia, and LatAm went through at comparable stages, and may require us to adjust. We’re likely to see: domestic strategic roll-ups at modest valuations, regional strategics doing the larger built-rails deals, PE for the profitable middle, and a slow build of public-market liquidity for the largest infrastructure plays. Africa will produce companies and exits we can’t currently model, and AI may rewrite parts of the framework. What I’m reasonably confident about is the structural logic: acquirers buy what they can integrate, and integration capacity is a function of pre-existing rails.
The past is never a full predictor of the future, but it can teach a lot, and sometimes help to frame better strategic choices in real time. I will be on the lookout for the next African tech IPOs of scale and some more potential acquirers like MTN entering the arena. The Stears gives us the ‘history of African exits’ map with new precision. The question it invites, for me, is the match between what gets built and who can buy it, and how founders, funds, DFIs and the report itself can sharpen that match over time. We’re walking with more open eyes than we were a year ago. The Stears exits map is a meaningful part of why.
Cross-regional comparisons are necessarily directional. Deal disclosure standards vary by jurisdiction and underlying data quality differs. Where deal values are estimates from TechCrunch or comparable trade press, this is noted in the body. As always, these are my interpretations, and I would genuinely welcome yours.
This is a standalone piece, separate from the Walk Together trilogy. For more on the rails framework, see “Walk Together. With Open Eyes.”
Sources and references.
Report and prior writing
Stears and Ventures Platform, 2025 Africa Venture Capital Exit & Liquidity Report: https://www.stears.co/info/2025-africa-venture-capital-exit-and-liquidity-report/
Walk Together. With Open Eyes. (the rails framework, founder-side): https://idosum.substack.com/p/walk-together-with-open-eyes
Named African exits and deals
Stripe acquires Paystack ($200M+, Oct 2020): https://stripe.com/newsroom/news/paystack-joining-stripe
BioNTech acquires InstaDeep (£562M, Jan 2023): https://techcrunch.com/2023/01/10/biontech-acquires-tunisian-born-and-u-k-based-ai-startup-instadeep-for-562m/
Medius acquires Expensya (Jun 2023): https://techcabal.com/2023/06/08/expensya-acquisition/
WorldRemit acquires Sendwave ($500M, Aug 2020): https://techcrunch.com/2020/08/19/worldremit-buys-fintech-sendwave-for-500m-to-expand-money-transfers-in-african-markets/
dLocal-AZA Finance, $23M Cameroon close (Feb 2026): https://launchbaseafrica.com/2026/03/19/a-23m-pivot-dlocal-takes-aza-finances-cameroon-assets-after-third-party-suit-is-dropped/
dLocal-AZA, FTX lawsuit context: https://weetracker.com/2026/03/23/dlocal-ftx-lawsuit-africa-deal-debt-conversion/
Network International acquires DPO Group ($288M, Jul 2020): https://gulfnews.com/business/banking/network-international-to-acquire-africas-leading-online-commerce-platform-dpo-for-288m-1.1595955372576
Dubizzle Group acquires Hatla2ee (Feb 2025): https://www.dubizzlegroup.com/dubizzle-group-acquires-egypt-automotive-platform-hatla2ee/
Baims acquires Orcas (Jan 2024): https://www.wamda.com/2024/01/kuwaiti-edtech-baim-acquires-egypts-orcas
Nedbank acquires iKhokha (~$93.9M, Aug 2025): https://group.nedbank.co.za/news-and-insights/press/2025/nedbank-acquires-ikhokha.html
Flutterwave acquires Mono (Jan 2026): https://techcrunch.com/2026/01/05/flutterwave-buys-nigerias-mono-in-rare-african-fintech-exit/
FairMoney acquires PayForce (Mar 2023): https://techcrunch.com/2023/03/14/nigerian-credit-led-fintech-fairmoney-acquires-payforce-in-retail-merchant-banking-play/
Risevest acquires Hisa (Sep 2024): https://techtrendske.co.ke/2024/09/18/nigerian-investment-firm-risevest-completes-acquisition-of-kenyas-hisa/
Stitch acquires Efficacy Payments (Jul 2025): https://techcabal.com/2025/07/09/stitch-acquires-efficacy-payments/
OmniRetail acquires Traction Apps (Oct 2024): https://thepaypers.com/payments/news/omniretail-acquires-traction-apps
MFS Africa (Onafriq) acquires Capricorn Digital/Baxi (2022): https://onafriq.com/press/article/mfs-africa-completes-capricorn
Oui Capital partial exit on Moniepoint Series C ($8M from $150K seed): https://techcrunch.com/2025/01/19/oui-capital-return-fund-with-moniepoint-exit/
TechCabal, 60 major M&A deals in Africa’s tech ecosystem in 2025: https://techcabal.com/2026/01/06/aquisitions-in-africas-tech-ecosystem-in-2025/
Cross-regional benchmarks
Walmart-Flipkart ($16B, May 2018): https://corporate.walmart.com/news/2018/05/09/walmart-to-invest-in-flipkart-group-indias-innovative-ecommerce-company
Alibaba-Lazada (cumulative ~$4B, 2016-2018): https://techcrunch.com/2018/03/18/alibaba-doubles-down-on-lazada/
ByteDance-Tokopedia ($1.5B, Dec 2023): https://www.bloomberg.com/news/articles/2023-12-11/tiktok-to-invest-1-5-billion-in-indonesia-shop-pact-with-goto
Uber-Careem ($3.1B, Mar 2019, SEC 8-K disclosure): https://www.sec.gov/Archives/edgar/data/0001543151/000162828019007371/uberq119earningspressrelea.htm
Amazon-Souq ($580M, Mar 2017): https://techcrunch.com/2017/07/03/amazon-souq-com-completed/
Uber-Cornershop (initial 51% deal Oct 2019, full buyout 2021): https://www.cbinsights.com/research/uber-acquires-cornershop/
StoneCo IPO (NYSE, Oct 2018, F-1 filing): https://www.sec.gov/Archives/edgar/data/0001745431/000119312518289511/d580263df1.htm
StoneCo-Linx ($1.1B, Aug 2020): https://www.leadersleague.com/en/news/stone-acquires-linx-in-brazil-s-largest-m-a-deal-of-2020
Nubank IPO (NYSE, Dec 2021, ~$41.5B valuation at pricing): https://www.cnbc.com/2021/12/09/buffett-backed-nubank-rises-in-trading-on-the-nyse-in-blockbuster-ipo.html
HDFC merger (Jul 2023): https://www.hdfc.bank.in/press-release/2023/q2/hdfc-ltd-to-merge-into-hdfc-bank-effective-july-1-2023
PayU-BillDesk termination ($4.7B, Oct 2022): https://www.business-standard.com/article/companies/india-s-largest-fintech-m-a-deal-falls-through-payu-calls-off-billdesk-buy-122100300422_1.html
Public market and exchange data
Fawry IPO (EGX, Aug 2019, first Egyptian fintech listing): https://www.egypttoday.com/Article/3/73707/Egyptian-investors-allocate-80-of-Fawry-s-IPO-EGX
Valu listing via EFG Holding in-kind distribution (Jun 2025), Amazon 3.95% stake: https://efgholding.com/en/media/news/ValuIPO
Bosta planned EGX listing (~$160-170M, end-2026): https://launchbaseafrica.com/2026/02/02/egyptian-logistics-startup-bosta-eyes-170m-ipo-on-local-exchange/
NGX market cap and largest companies (Aug 2025): https://businessday.ng/companies/article/full-list-of-nigerian-companies-with-market-capitalization-above-1-billion/
EGX top 50 market cap, $30.4B (Forbes ME): https://english.ahram.org.eg/News/503025.aspx
MNT-Halan EGX IPO consideration: https://launchbaseafrica.com/2024/07/30/mnt-halan-eyes-egyptian-stock-exchange-listing-targets-1-billion-financing-portfolio/
Industry reports referenced (not hyperlinked individually): AVCA 2024 African Private Capital Activity Report; Partech Africa 2024 Africa Tech Venture Capital Report; LAVCA 2025 Industry Data and Highlights; Bain India Venture Capital Report 2025; DealStreetAsia SE Asia Deal Review.